Market Overview: Definition and Industry Significance of Collapsible Metal Tubes
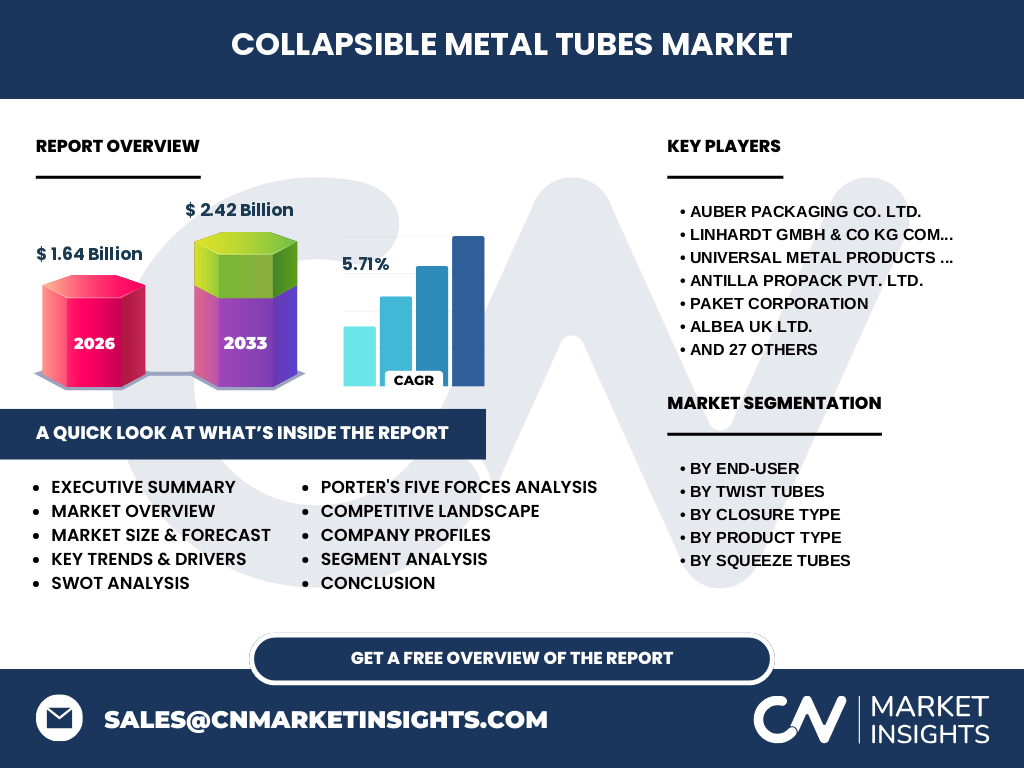
The Collapsible Metal Tubes Market encompasses high-barrier, flexible packaging solutions primarily manufactured from aluminum or tin. Serving as a critical protector for sensitive formulations in pharmaceuticals and cosmetics, these tubes offer superior shelf-life by preventing oxidation. With a 2026 market valuation of 1.64 Billion, their significance lies in providing an airtight, tamper-evident barrier that maintains ingredient integrity against light, moisture, and chemical degradation.
Structural Growth Drivers and Market Constraints
Growth is fueled by the 5.71% CAGR projected through 2033, driven by an escalating demand for sustainable, recyclable metal packaging. However, the market faces logistical hurdles related to raw aluminum price volatility and the complexity of managing global supply chains through major ports. Opportunities exist in premiumizing pharmaceutical dispensing, while restrictive regulatory environments in the EU regarding aerosol metal recycling present notable operational challenges for manufacturers.
Emerging Trends Shaping the Industry Landscape
A pivot toward sustainable, mono-material packaging defines the current landscape. Customization is peaking as brands demand intricate branding on squeeze tubes. Companies like Hoffmann Neopac AG are leading with advanced printing technologies that allow for high-resolution aesthetics on metal surfaces. This shift reflects a broader consumer preference for eco-friendly packaging that balances luxury visual appeal with the structural robustness required for long-term product preservation.
COVID-19 Impact and Recovery Trajectory
The pandemic acted as an accelerator for high-hygiene packaging. While initial lockdowns disrupted supply chains, the subsequent surge in demand for specialized pharmaceutical ointments and sanitizing creams bolstered the sector. Our research indicates a resilient recovery trajectory, with the industry rebounding to reach a projected 2.42 Billion by 2033. This period forced manufacturers to diversify supplier bases to mitigate future global shocks.
Competitive Benchmarking and Strategic Dynamics
The market remains highly fragmented with a mix of multinational giants and niche regional specialists. Players like Alltub SAS and Linhardt GmbH & Co KG exert significant pressure through extensive R&D in barrier coating. Strategic competition revolves around automation efficiency and rapid scaling. Firms that integrate vertically—controlling the production of both the body and the closure—demonstrate higher margins and stronger market resilience against raw material cost fluctuations.
Executive Summary of the Collapsible Metal Tubes Market
The Collapsible Metal Tubes Market is poised for a robust expansion from 1.64 Billion in 2026 to 2.42 Billion by 2033. Driven by a 5.71% CAGR, the sector is defined by its transition toward sustainability and high-barrier integrity. Pharmaceutical and cosmetic end-users remain the primary growth engines, while innovation in nozzle and flip-top cap design continues to differentiate legacy players in a competitive, globalized market environment.
Financial Projections: Market Forecast 2027-2033
With a steady CAGR of 5.71%, we forecast the market to reach 2.42 Billion by 2033. This trajectory assumes consistent growth in emerging economies and high penetration rates in the pharmaceutical sector. Our analysis suggests that while industrial demand remains flat, the Cosmetics and Personal Care segments will provide the necessary volume to sustain this aggressive growth profile through optimized distribution networks.
Segmentation Analysis: Categorizing Market Performance
Segmentation is categorized by End-User (Home Care, Cosmetics, Industrial, Pharmaceutical), Product Type (Twist vs. Squeeze), and Closure Type (Fez, Nozzle, Flip Top). The Pharmaceutical segment acts as the primary anchor, demanding stringent regulatory compliance, while Squeeze Tubes dominate the volume metrics. Each segment plays a specific role, with custom variations serving the high-end cosmetic market to boost per-unit value and brand loyalty.
Regional Market Performance and Distribution
The Asia-Pacific region is emerging as the highest-growth geography due to rapid industrialization in packaging infrastructure. Conversely, North America and Europe remain mature markets, focusing on sustainable material innovation. Geographic performance is heavily linked to the proximity of aluminum smelting sites and the presence of major regional distribution hubs. Our data indicates that regional disparities are primarily driven by varying local health regulations and cosmetic market saturation levels.
In-Depth Regional Review of Key Markets
In Europe, Linhardt GmbH & Co KG benefits from strict recycling directives, pushing the adoption of high-recycled-content tubes. In the Asia-Pacific theater, Guangzhou Amy Plastic Tube Co. Ltd. and other local innovators benefit from massive scalability in the home care and cosmetics sectors. North American markets show high demand for Custom Twist Tubes, reflecting the region's preference for branded, premium consumer goods that utilize advanced, consumer-friendly closure technologies.
Company Profiles and Strategic Positioning
Strategic leaders like Amcor Limited and CCL Industries Inc. leverage global economies of scale to dominate, whereas specialists like Universal Metal Products Inc. focus on niche high-barrier technology for specialized pharmaceuticals. These companies are increasingly investing in automated production lines to offset labor costs. Their positioning is dictated by a clear split between commodity-grade squeeze tube mass production and high-value, bespoke pharmaceutical packaging that requires specific ISO-certified manufacturing environments.
Porter's Five Forces Assessment
The industry exhibits moderate-to-high competitive rivalry, balanced by significant barriers to entry due to capital-intensive machinery requirements. Buyer power is high among large-scale cosmetic conglomerates, while supplier power for aluminum stock is volatile. The threat of substitutes, particularly laminated plastic tubes, remains a critical force, compelling metal tube manufacturers to emphasize the superior environmental footprint and barrier properties of aluminum to maintain market share.
SWOT Analysis of the Metal Tubes Sector
Strengths: Unrivaled barrier properties and high recyclability. Weaknesses: Sensitivity to aluminum pricing. Opportunities: Expanding into the burgeoning organic cosmetic market that demands preservative-free, stable packaging. Threats: Rapidly improving multi-layer plastic composites which offer lower price points. Successfully navigating these factors requires firms to double down on the sustainability narrative, positioning metal as the premium, eco-responsible alternative to plastic variants.
Value Chain Analysis: From Raw Material to End-User
The value chain originates with aluminum slug procurement, which is then processed through extrusion and coating. Value is added during the shaping and printing phases, where branding dictates a significant portion of the cost. Distribution flows through intermediaries to major cosmetic and pharmaceutical manufacturers. Our analysis shows that firms controlling the proprietary nozzle and closure injection molding capture the highest margin, as these represent the final functional touchpoint for the end-user.
Investment Insights and High-Potential Areas
Investors should target high-barrier pharmaceutical packaging facilities that hold cGMP certifications. There is significant untapped potential in the Custom Squeeze Tube sector, particularly for clean-label beauty brands. Strategic recommendations suggest prioritizing firms that demonstrate closed-loop recycling capabilities, as regulatory bodies are tightening mandates on the circular economy. These companies are best positioned to outperform the 5.71% CAGR as sustainability becomes a non-negotiable procurement criterion.
Conclusion and Strategic Takeaways
The Collapsible Metal Tubes Market is experiencing a period of vital transformation. Key takeaways include the inevitability of the 1.64 Billion to 2.42 Billion valuation shift, the necessity of sustainability-led innovation, and the critical importance of regional logistics. Organizations that prioritize flexible, high-speed manufacturing while maintaining the rigorous barrier standards required by the pharmaceutical sector will be the long-term beneficiaries of the ongoing market evolution.
Research Methodology: How Baseline Estimates are Triangulated
Our estimates are built through triangulation of proprietary trade registry data, interviews with C-suite executives at major manufacturing firms, and analysis of regional macroeconomic indicators. We cross-reference production volume reports from key ports with customs data to validate regional output. This ensures our 5.71% growth forecast accounts for both supply-side manufacturing shifts and demand-side consumption patterns in the pharmaceutical and cosmetic industries.
Scope of the Report: Parameters and Limitations
This report covers the global Collapsible Metal Tubes Market, focusing on squeeze and twist tubes across all primary end-use sectors. The scope is bounded by 2026-2033, analyzing market dynamics, competitive positioning, and regional trends. Limitations include the variability of informal, local-market supply chains in developing regions, which are estimated based on proxy data from secondary macroeconomic sources to ensure a comprehensive global picture.
Recent Developments: Industry Announcements and Partnerships
Recent activity is dominated by strategic capacity expansions. Essel Propack and Hoffmann Neopac have recently announced partnerships focusing on next-gen lightweight aluminum alloys. These developments aim to improve material efficiency and lower shipping weights. Furthermore, the launch of recyclable, tamper-evident flip-top closures signals a move toward addressing the specific needs of the pharmaceutical sector, effectively creating new barriers to entry for low-cost, standard-cap competitors.